

Important security note: Warning of attempted fraud in the name of DWS
We have detected that fraudulent individuals are misusing the "DWS" trademark and the names of DWS employees on the internet and social media. These fraudsters are operating fake websites, Facebook pages, WhatsApp groups and Mobile Apps. Please be aware that DWS does not have any Facebook Ambassador profiles or WhatsApp chats. If you receive any unexpected calls, messages, or emails claiming to be from DWS, exercise caution and do not make any payments or disclose personal information. We encourage you to report any suspicious activity to info@dws.com, including any relevant documents and the original fraudulent email. Additionally, if you believe you have been a victim of fraud, please notify your local authorities and take steps to protect yourself.
CIO View Portfolio: Perspectives
9/30/2026
In our monthly Multi-Asset update we show the implementation of our CIO View in the CIO View model portfolio.

Vincenzo Vedda
Chief Investment Officer
Overview
Idea of the month
Emerging-market bonds continue to offer attractive income opportunities in our view. Over a 12-month horizon, total returns approaching double digits appear achievable, supported by solid global growth, positive rating trends and the prospect of a weaker U.S. dollar. That said, much of the good news is already reflected in valuations. For sovereign bonds, the scope for further spread compression looks limited, particularly as geopolitical tensions and higher U.S. real yields could act as headwinds. Asian corporate bonds continue to benefit from strong fundamentals, robust regional demand and limited new issuance. Their attractiveness, however, lies primarily in carry rather than further price appreciation.
Sources: Bloomberg Finance L.P., DWS Investment GmbH as of 9/10/26
Our take on duration & risk
Risk
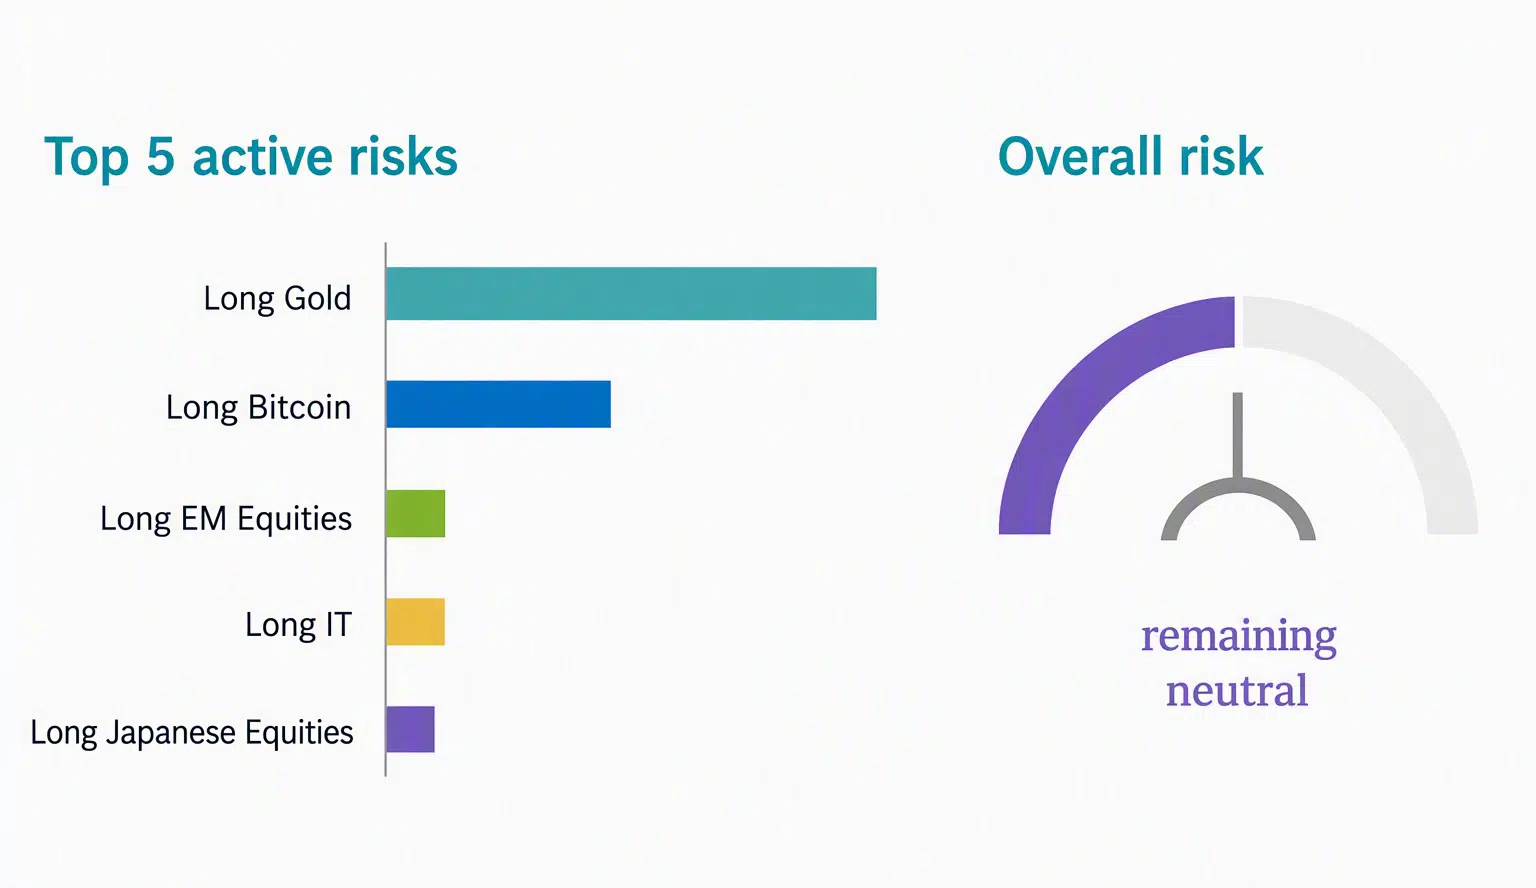
Resilient growth, robust earnings and continued AI-related investment remain supportive for equities. However, investor positioning is already constructive and much of the positive news appears priced in. Key risks include uncertainty around the Fed, further upward pressure on bond yields and unresolved Middle East tensions, which could keep energy prices elevated. Higher yields and energy costs may weigh on valuations and consumer spending. With limited earnings catalysts and seasonality typically less supportive during the U.S. midterm election period, the overall risk-reward profile remains broadly balanced despite solid fundamentals.
We stick to our risk preference at neutral
Source: DWS Investment GmbH as of Sept 16, 2026
Duration
Attractive yield levels and our view that markets are pricing more policy tightening than implied by the DWS base case remain supportive for duration in our view. However, uncertainty around the Fed, elevated rate volatility and the risk of higher yields argue for caution. Middle East tensions could also keep energy prices and inflation elevated. In an environment of resilient growth, duration currently offers limited diversification benefits. We therefore favor the 2- to 5-year segment and maintain a preference for curve steepeners, particularly in 5s30s and 10s30s, as term premia are likely to rebuild further.
We lower our duration preference to neutral

Source: DWS Investment GmbH as of Sept 16, 2026
What’s up in the segments?
Balanced, but moderately constructive on equities. Tech upgraded to +1.
We retain a balanced but moderately constructive stance on equities. While strong earnings, resilient growth and reasonable valuations continue to support markets, several near-term headwinds argue for caution, including interest-rate uncertainty, geopolitical risks, investor positioning, seasonality and the approaching U.S. midterm elections. Q2 earnings exceeded expectations on both sides of the Atlantic, led by Technology, Energy and Financials in the U.S. and broad-based strength in Europe. We upgrade Information Technology to +1, as temporary concerns around AI monetization have created more attractive valuations while earnings expectations remain supportive. Regionally, we continue to favor Emerging Markets and Japan, supported by stronger earnings growth and attractive relative valuations. Utilities remain a preferred diversifier, benefiting from rising electricity demand linked to AI and still supportive valuations. Global banks also stand out due to solid growth prospects and attractive pricing. While Europe has become more interesting following strong earnings and improving macro surprises, we remain neutral for now and keep some dry powder for potential opportunities ahead. In fixed income, we prefer high-quality credit over high yield. EUR IG remains favored over USD IG due to stronger technicals, while EM hard-currency sovereign debt has been upgraded to +1 following wider spreads and improved valuations. In a multi-asset context, we are neutral on EUR/USD given the potential diversification benefits due to geopolitical risks.
Interesting developments in global bond markets
Source: Bloomberg Finance L.P., DWS Investment GmbH as of 9/10/26
Source: Bloomberg Finance L.P., DWS Investment GmbH as of 9/10/26
CIO View Model Portfolio positioning vs. anchor
This allocation shows how we implement the above-mentioned CIO View into a Multi-Asset portfolio of liquid securities.
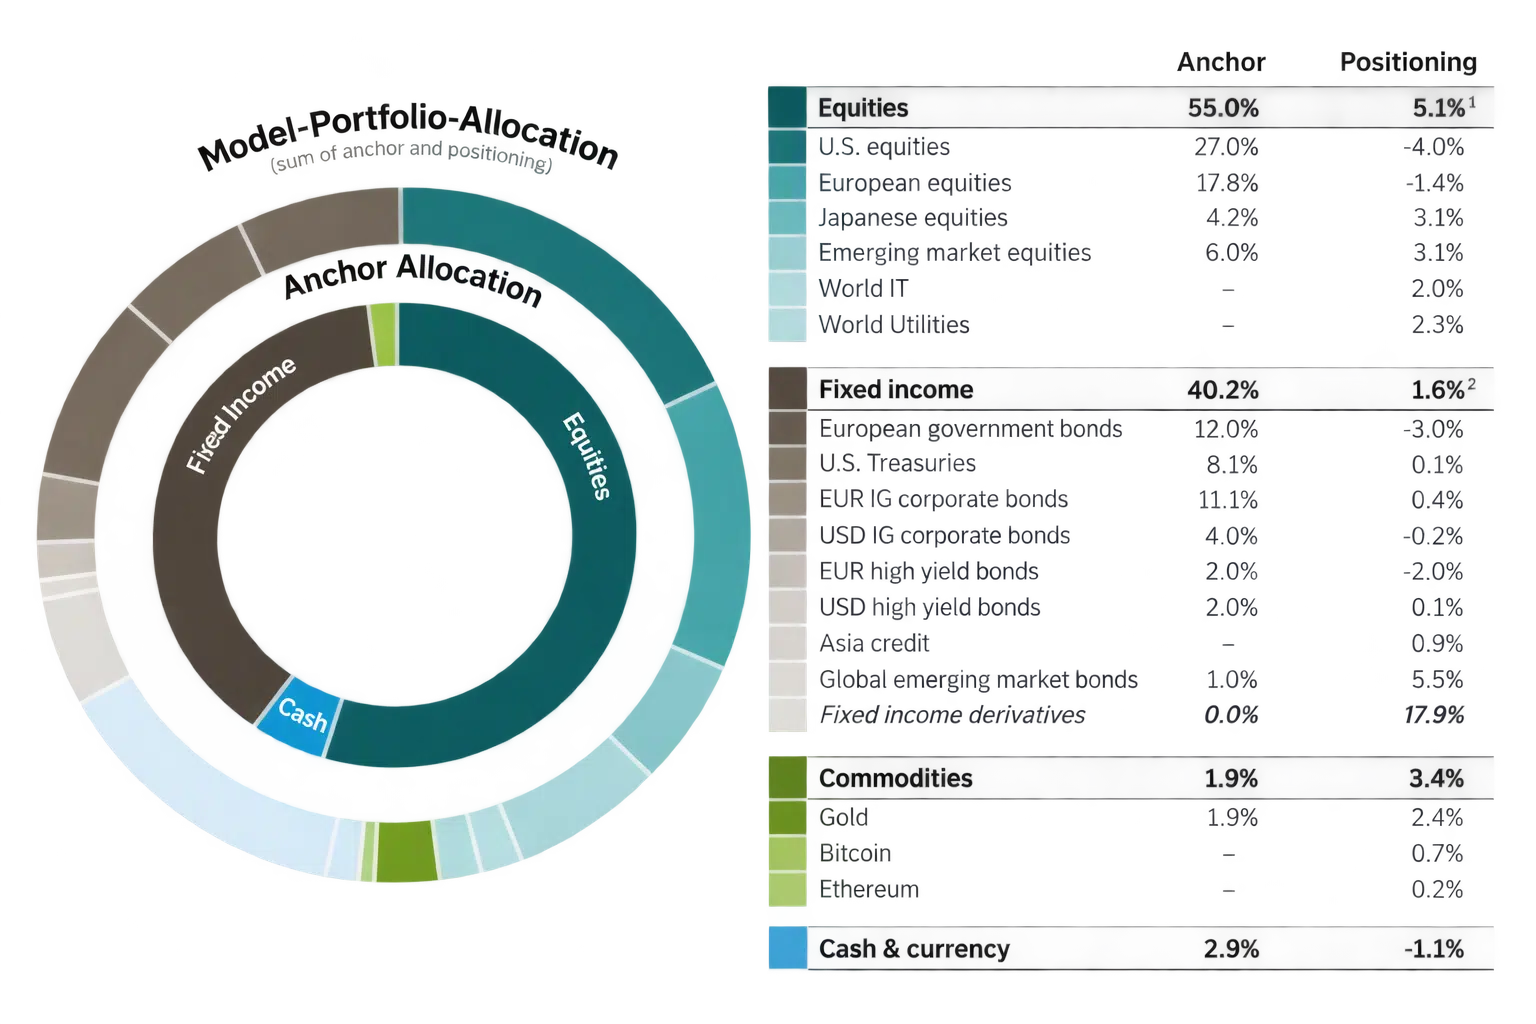
This allocation may not be suitable for all investors and can be changed at any time without notice. Source: DWS Investment GmbH, as of Sept 16, 2026.The anchor allocation refers to the strategic asset allocation, while the portfolio positioning refers to the tactical asset allocation. Rounded figures. Including equity derivatives.
1 Total excluding interest rate derivatives
2 (derivatives are included in the positioning figures at a subordinate level).