
Important security note: Warning of attempted fraud in the name of DWS
We have detected that fraudulent individuals are misusing the "DWS" trademark and the names of DWS employees on the internet and social media. These fraudsters are operating fake websites, Facebook pages, WhatsApp groups and Mobile Apps. Please be aware that DWS does not have any Facebook Ambassador profiles or WhatsApp chats. If you receive any unexpected calls, messages, or emails claiming to be from DWS, exercise caution and do not make any payments or disclose personal information. We encourage you to report any suspicious activity to info@dws.com, including any relevant documents and the original fraudulent email. Additionally, if you believe you have been a victim of fraud, please notify your local authorities and take steps to protect yourself.
A differentiated look at the IT sector
07/08/2026
Our CROCI analysis highlights the importance of valuation assumptions

Semiconductor manufacturing is notoriously temperature sensitive. Lately, semiconductor stocks have been, too. After a strong spring rally[1] in which the Philadelphia Semiconductor Index (SOX) more than doubled, the market turned down the thermostat in July, wiping out nearly a third of those gains.[2] Even so, the Index was more than 70% higher year to date, and this is before this week’s rebound. This volatility provides a timely opportunity to take a look at IT valuations.
In DWS’s CIO View, we had become cautious because of the high valuations in the semiconductor space earlier in the summer, but we are now taking the opportunity to upgrade the segment again and with it the overall IT sector, on which we now hold a positive view.
From a CROCI perspective, which seeks to place companies on a more comparable footing by adjusting for accounting differences, this Chart of the Week compares median 2026 expected Economic price-to-earnings (P/E) multiples across non-financial developed market sectors. Viewed through this lens, the contrast is stark. The IT sector trades on 41.8x – the highest valuation in the CROCI universe. Health care is on the other side of the spectrum, trading on 26.7x. Based on this metric, investors are paying around 56% more for the average IT company than for the average health care company.
Semiconductors remain a key driver of IT’s premium. The median company trades on roughly 49x 2026 expected economic earnings, over 15% above the sector average. In our view, that reflects continued confidence in AI-driven demand, investment and earnings growth.
Looking further ahead and at the aggregate vs. the median, the picture changes, however. Based on current aggregate 2027 estimates, IT’s valuation premium (based on the CROCI methodology) over the broader market largely disappears, as profitability is forecast to improve significantly at some of the world’s largest technology companies.
As Benjardin Gärtner, Global Head of Equity, notes: ”For investors, the key question is not which sector has the better story, but whether current prices fairly reflect future opportunities and risks.”
Judged by the median 2026 expected Economic P/E ratio, the IT sector has the highest valuation
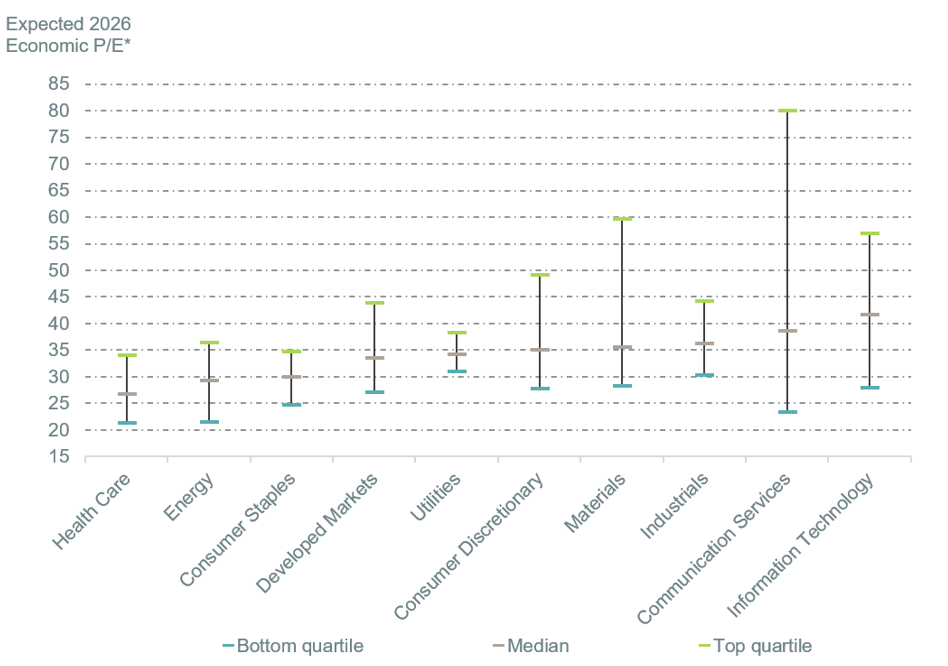
Sources: DWS Investment GmbH, CROCI as of August 4, 2026
*For each of the sectors, the median, 75th and 25th percentile Economic P/E are displayed. The CROCI developed markets non-financial coverage universe comprises approximately 700 companies, covering around 80% of the constituents of the MSCI World non-financial index.
This information is subject to change at any time, based upon economic, market and other considerations and should not be construed as a recommendation. Past performance is not indicative of future returns. Forecasts are based on assumptions, estimates, opinions and hypothetical models that may prove to be incorrect. Alternative investments may be speculative and involve significant risks including illiquidity, heightened potential for loss and lack of transparency. Alternatives are not suitable for all clients.