
Important security note: Warning of attempted fraud in the name of DWS
We have detected that fraudulent individuals are misusing the "DWS" trademark and the names of DWS employees on the internet and social media. These fraudsters are operating fake websites, Facebook pages, WhatsApp groups and Mobile Apps. Please be aware that DWS does not have any Facebook Ambassador profiles or WhatsApp chats. If you receive any unexpected calls, messages, or emails claiming to be from DWS, exercise caution and do not make any payments or disclose personal information. We encourage you to report any suspicious activity to info@dws.com, including any relevant documents and the original fraudulent email. Additionally, if you believe you have been a victim of fraud, please notify your local authorities and take steps to protect yourself.
Investment Traffic Lights
09/09/2026
The monthly Investment Traffic Lights provide a detailed market analysis and our view on developments in the main asset classes.
IN A NUTSHELL
- Resilient growth, strong earnings and continued AI enthusiasm drove global equities higher and kept corporate credit spreads tight in August, despite persistent geopolitical and inflation uncertainty.
- Government bond markets told a different story as the 30-year Treasury reached 5.34%, its highest since 2007, amid fiscal and inflation concerns.
- Our updated forecasts remain constructive across asset classes, with equity returns driven primarily by earnings growth and attractive income opportunities in fixed income.

Vincenzo Vedda
Chief Investment Officer

Page summary
1. Market overview
1.1 Strong growth and robust markets, but higher bond yields are a cause for concern.
If one number were to sum up August, it might be 5.34%. This was the peak yield reached by the 30-year U.S. Treasury on August 18, 2026, its highest level since 2007. At first glance, this may seem difficult to reconcile with the broader market backdrop. Economic activity remained surprisingly resilient, corporate earnings generally exceeded expectations, and most major equity markets posted gains over the month. Yet, beneath this solid performance by risk assets, bond investors appeared increasingly concerned about stubborn inflation pressures, rising fiscal deficits and the prospect of higher interest rates for longer.[1]
Equity investors, for their part, had several reasons to remain optimistic. Purchasing Managers' Index (PMI) surveys suggested that growth momentum had strengthened further on both sides of the Atlantic. In the United States, the flash composite PMI reached its highest level in more than four years, while the equivalent Eurozone measure reached a nine-month high. Corporate earnings also provided support, particularly within the technology sector. The Magnificent Seven rose by more than four percent during the month, once again helping to drive broader U.S. equity indices higher. Meanwhile, South Korea’s KOSPI 100 emerged as one of the strongest-performing markets globally, benefiting from a continued boom in semiconductor exports and investor enthusiasm for AI-related growth opportunities. Overall, global equities largely shrugged off geopolitical uncertainty and rising government bond yields. Even the Philadelphia Semiconductor Index, which had experienced significant volatility earlier in the year, ended August in positive territory.
However, bond markets arguably told the more interesting story. Long-term government bond yields rose across much of the developed world. Germany's 30-year Bund yield climbed to levels last seen in 2011, while French and Italian government bonds underperformed their U.S. counterparts. Yields also rose significantly in Japan as investors increasingly anticipated further policy tightening by the Bank of Japan (BoJ). The broad increase in yields was particularly noteworthy because it occurred despite only limited evidence of a marked deterioration in economic conditions. Instead, investors appeared to focus more closely on inflation risks and growing government debt burdens. Concerns over fiscal sustainability resurfaced in several regions, while central banks maintained a hawkish tone and markets moved to price in another European Central Bank (ECB) rate increase.
Commodity markets added to inflation concerns. The closure of the Strait of Hormuz fueled supply concerns and contributed to significant rises in agricultural commodity prices. Wheat, corn and sugar all recorded unusually strong monthly gains, indicating that inflationary pressures were not confined to the energy sector. Investors became increasingly aware that geopolitical tensions could be transmitted through food prices as well as energy costs. While Brent crude ended the month little changed overall, it experienced considerable intra-month volatility. Taken together, developments across commodity markets pointed to upside risks to the inflation outlook.
Against this backdrop, some investors sought protection in assets traditionally perceived as a safe haven.[2] Gold posted a strong monthly gain, while silver outperformed most major asset classes. The rally appeared to reflect inflation concerns, as well as the broader debate around financial repression and government debt dynamics. Credit markets, however, remained remarkably calm. Investment-grade (IG) and high-yield (HY) spreads both stayed tight, suggesting that investors saw little near-term risk of a sharp economic slowdown or a meaningful deterioration in corporate fundamentals. This contrast between credit and sovereign bond markets may prove to be one of the defining characteristics of the current market environment.
August served as a reminder that markets can be driven by several narratives simultaneously. On the one hand, economic growth remains resilient, earnings continue to exceed expectations, and enthusiasm around artificial intelligence (AI) continues to support equity valuations. On the other hand, higher long-term yields suggest that investors are becoming less comfortable with rising government debt, persistent inflation risks and the long-term consequences of increasingly expansionary fiscal policies. In our view, bond investors are currently sending a more cautious message than equity markets appear willing to acknowledge. The key question for the remainder of the year is whether equities can continue to rise if borrowing costs stay elevated.
In this video: key drivers behind market resilience
2. Outlook and changes
As this is the quarterly edition of our Investment Traffic Lights, we will concentrate on setting out our updated 12-month outlook, while also explaining the most important recent changes in our asset-class views.
The global economy has absorbed the energy shock better than most anticipated, and continued expansion remains our base case. We forecast global gross-domestic-product (GDP) growth of 3.0% in 2026 and a modest acceleration to 3.3% in 2027. The U.S. economy should grow 2.1% this year and 2.0% next year, while Eurozone growth should increase from 0.9% to 1.3%. Higher energy costs continue to erode household purchasing power, yet there remains little evidence that the initial price shock has propagated into broader and more persistent inflation.
We revised Germany’s 2026 growth forecast up to 1.3%, though the upgrade largely reflects historical revisions, a stronger second quarter and the use of non-calendar-adjusted figures rather than a meaningful underlying improvement. China should grow 4.6% in 2026 and 4.5% in 2027, with soft domestic demand leaving growth disproportionately reliant on exports and fiscal support.
Monetary policy remains the central macro debate. We expect the U.S. Federal Reserve (the Fed) to hike once through September 2027. The case for a rate increase rests less on the underlying economic data than on the Fed’s determination to emphasize its inflation credibility. Weakness in housing, consumption and parts of the labor market should limit the scope for further tightening, and we do not anticipate a broader hiking cycle. In the Eurozone, we expect the ECB to hike once to 2.5%, followed by an extended pause.
Beneath this resilient headline picture, economic momentum is bifurcating. We believe that AI investment continues to anchor U.S. growth, corporate earnings and power demand, while consumption, housing and parts of the labor market lose impetus. At the same time, the growth rate of AI capital expenditure may be approaching a peak, even as absolute spending levels continue to rise. The next phase of the cycle hinges on whether adoption, monetization and productivity gains can justify the scale of investment already committed.
We characterize this environment as late-cycle Goldilocks: growth remains positive and inflation is gradually moderating, but elevated yields and geopolitical uncertainty are narrowing the margin for error. Strong earnings continue to underpin equities, while higher government-bond yields have restored the appeal of fixed income. The result is a supportive but increasingly differentiated investment environment.
2.1 Fixed Income
Global interest-rate developments should continue to be shaped by the tension between persistent inflation risk and waning growth momentum. Inflation should moderate further, but durable nominal growth, substantial government borrowing and strong demand for capital could sustain yields above the levels of previous cycles. Restrictive financing conditions, meanwhile, bear most heavily on the rate-sensitive parts of the U.S. economy, which may shift attention from inflation toward growth.
Monetary policy paths are likely to differ by region. In the Eurozone, still-elevated inflation should prompt one further rate increase before the ECB pauses. In the United States, we expect one hike to reinforce the Fed’s commitment to its inflation target, although softer economic data should limit further tightening.
Government Bonds
Fiscal and structural forces now shape the government-bond markets alongside the traditional growth and inflation cycle. Large deficits, rising debt levels and substantial borrowing requirements are lifting term premia across developed markets, limiting how far long-term yields can decline even as central banks approach the end of their tightening cycles.
In the United States, Treasury yields should settle near the middle of their recent range over the next 12 months. Softer activity and moderating inflation should eventually provide support, but persistent fiscal deficits, heavy issuance and strong demand for capital are likely to keep longer-dated yields elevated. Our September 2027 forecasts are 4.0% for the two-year and 4.5% for the 10-year. We remain constructive on the front and intermediate portions of the curve, although the prospect of a Fed hike argues against expecting a pronounced decline in short-term yields.
In Europe, a final ECB hike should reinforce inflation credibility, while slowing growth and moderating inflation support a gradual decline in front-end yields. Higher issuance, defense spending and broader fiscal concerns should limit the decline at the long end. We therefore continue to prefer front-end duration.
The outlook for UK Gilts remains constructive, as slowing domestic demand and a weaker labor market should draw yields down from their current highs. We have turned more positive on short-dated Gilts as market pricing appears too hawkish relative to our expectation that the Bank of England (BoE) will stay on hold.
Japan remains the major exception among developed markets. Japanese government-bond (JGB) yields should rise further as the Bank of Japan (BoJ) pursues normalization and reduces its bond purchases. We expect Japan policy rates to rise to 1.75% over the next 12 months.
Source: Bloomberg Finance L.P., DWS Investment GmbH as of 9/4/26
Corporate Bonds
In the U.S., we expect investment-grade (IG) spreads to remain range-bound, supported by resilient corporate fundamentals and continued demand for attractive all-in yields. Heavy issuance associated with AI-related investment and still-tight valuations nonetheless limit the scope for further spread compression. We continue to favor carry, security selection and shorter-to-intermediate maturities over broad market exposure. In high-yield (HY), robust technicals and healthy fundamentals should continue to provide support , although tight spreads leave limited cushion if fundamentals soften, and we continue to favor a selective approach.
European investment-grade spreads should likewise hold near current levels, reinforced by healthy balance sheets, low default expectations and durable investor demand. Rising government-bond yields, growing supply and AI-related financing needs constitute a less accommodating technical backdrop, and we see limited scope for tightening from here. In high yield, spreads are also expected to remain near current levels, supported by strong technicals and investor demand, although investors are becoming more discriminating as valuations stay rich and downside risks accumulate. Default rates should remain contained, while recovery values seem to be converging toward their historical average of around 50%. From a tactical perspective, we downgraded EUR investment-grade credit from Positive to Neutral in August, reflecting limited upside at current valuations, and moved EUR high yield from Neutral to Negative as spreads no longer compensate investors adequately for the balance of risks in our view.
Credit spreads remain at tight levels Source: Bloomberg Finance L.P., DWS Investment GmbH as of 9/4/26
Emerging Markets
Emerging-market (EM) sovereign spreads should remain broadly stable over the next 12 months. Resilient global growth, positive rating momentum and a potentially weaker U.S. dollar provide a favorable backdrop. However, much of this is already reflected in valuations, limiting the scope for further spread compression and supporting our Neutral strategic view. Nevertheless, with all-in yields at multi-year highs, we believe the income opportunity remains intact for long-term investors. Tactically, we upgraded EM sovereigns to Positive in early August after July’s widening created a more attractive entry point. This view assumes some easing of Gulf tensions, while we consider higher U.S. real yields and a steeper U.S. yield curve the principal risks.
Asia credit spreads should prove similarly stable, sustained by steady corporate fundamentals, strong regional demand and favorable technicals. High savings rates and improving fundamentals should absorb supply, as lighter-than-expected primary issuance keeps IG spreads tight. However, the asset class remains vulnerable to higher energy prices, geopolitical tensions and any re-escalation of trade tensions. With spreads near historical tights, our conviction rests on all-in yields and regional technical support. We stay constructive on the asset class, with a slight preference for HY over IG given its higher carry.
Currencies
We expect the U.S. dollar to weaken into the next 12 months. Refinancing requirements coinciding with large budget deficits have become a pressing consideration for the USD, while slowing AI spending growth reduces a primary source of capital inflows. These headwinds, alongside a modestly improved Eurozone outlook, favor EUR/USD, which we forecast at 1.20 by September 2027. To reflect this conviction also in our tactical view, we moved from Neutral to Positive on EUR/USD in late August.
In our view, the yen remains materially undervalued and should gradually recover, supported by further BoJ normalization. However, persistent capital outflows and a wide yield differential should constrain the extent of appreciation. We forecast USD/JPY at 150 by September 2027, up from our previous target of 145. Tactically, we reaffirmed our Negative view on USD/JPY in mid-August, as recent currency intervention has helped stabilize the yen, while expectations of further BoJ tightening provide additional support.
We also remain constructive on the Australian dollar, which is our preferred G10 currency. Strong fiscal and external balances, exposure to commodity demand, attractive carry and a reasonable valuation should all provide support over the medium term.
2.2 Equities
We anticipate a constructive environment for global equities through September 2027, but further returns should be driven primarily by earnings growth. The AI investment cycle remains the main support, while the latest reporting season showed earnings growth broadening beyond the Magnificent 7 and the wider technology sector. At the same time, high interest rates, substantial government and AI-related financing needs and exceptionally high semiconductor profitability argue against further broad-based multiple expansion in our view.
Our forecasts assume that the Strait of Hormuz remains at least partially open, developed economies grow around potential without entering recession and the 10-year U.S. Treasury yield remains below 5%. We assume no further expansion in U.S. equity multiples and some normalization in Asian semiconductor valuations, with above-trend earnings growth remaining the principal source of returns. The main downside scenario would be a prolonged disruption to Gulf shipping, oil prices above USD 150 per barrel and a renewed rise in inflation and bond yields.
U.S. Market
We see potential for the S&P 500 to reach 8,400 by September 2027. Earnings growth is strong and broadening, with AI still the largest single contributor. However, already elevated valuations, rising long-term yields and fiscal risks mean that further upside should come from earnings rather than multiple expansion.
European Market
We think the Stoxx Europe 600 could reach 690 by September 2027. Improving earnings momentum, particularly in financials, industrials and defense-related sectors, together with attractive shareholder distributions and a substantial valuation discount to the U.S. market, should continue to support European equities. However, limited exposure to the AI investment cycle and greater sensitivity to energy prices are likely to constrain a broader valuation rerating.
German Market
We see potential for the DAX to reach 28,600 by September 2027. Fiscal expansion, debt-brake reform, deregulation and improving real wages should support activity, but the index remains highly cyclical and exposed to weak Chinese demand, tariff uncertainty and structural pressure on automotive earnings. In our view, profitable growth companies with attractive earnings potential and solid balance sheets are best positioned.
Emerging Markets
We forecast that the MSCI Emerging Markets Index could reach 1,790 by September 2027. Earnings momentum is concentrated in Korean and Taiwanese technology companies, particularly semiconductors, while China has yet to deliver a broad earnings recovery. Following the strong AI-driven profit cycle, our forecast also assumes some normalization in valuations from current levels. From a shorter-term tactical perspective, we have moved Emerging Markets back to Neutral. This reflects the narrow earnings momentum and limited improvement outside the Asian technology complex. We also maintain a Neutral position in Asia ex Japan and China.
Japan
We see potential for the MSCI Japan Index to reach 2,760 by September 2027. Reflation, stronger domestic investment, corporate-governance reform and rising dividends and buybacks remain supportive, while exporters and technology companies continue to benefit from the global AI cycle. The principal risks are yen appreciation, faster BoJ tightening and Japan’s exposure to imported energy costs. We remain Positive on Japanese equities and believe that periods of short-term weakness would create attractive entry points.
Source: Bloomberg Finance L.P., DWS Investment GmbH as of 9/4/26
Sectors
We made two tactical sector changes in Q3. At the end of July, we upgraded Information Technology to Positive following its valuation correction, while moving Software & Services from Negative to Neutral. We continue to believe that the AI investment cycle is intact, although in our view greater selectivity is necessary as financing constraints, free-cash-flow discipline and the sustainability of exceptionally high semiconductor profitability come increasingly into focus.
2.3 Alternatives
Real Estate
We view the recovery in global real estate to be intact, though its pace has slowed under higher financing costs and geopolitical uncertainty. Fundamentals are sound, with low vacancy rates, limited new supply and rental growth expected across most sectors. Residential and logistics are our preferred areas, yet, within office, we see greater resilience in prime assets and locations. In our view, the United States offers a favorable near-term outlook, while higher interest rates create greater headwinds in Europe and parts of Asia-Pacific. Tactically, we remain Positive on listed real estate.
Infrastructure
Infrastructure should continue to benefit from electrification, rising power demand and investment in energy and digital networks. Necessity-based assets and inflation-linked revenues can provide stable cash flows, but elevated borrowing costs and geopolitical risks continue to constrain transaction activity. We therefore favor assets capable of sustaining and growing distributions and remain selective in areas such as fiber networks and renewable energy developers, where financing and operating pressures have become more visible.
Gold
We see potential for Gold to reach USD 5,000 per ounce by September 2027. Central-bank demand, concerns over fiscal deficits and potential currency debasement and continued diversification away from the U.S. dollar should provide long-term support. However, central banks have become more price-sensitive and elevated real yields could curb further appreciation in the near term. We therefore maintain our Neutral tactical view on Gold.
Oil
We think Brent crude could ease to USD 79 per barrel by September 2027, as negotiations should gradually permit shipping and supply to normalize and additional OPEC and non-OPEC production returns. Near term, however, the Strait of Hormuz remains disrupted and damage to refining infrastructure is keeping product markets tight. These risks support our Positive tactical view on Oil, even as the strategic outlook points to lower prices once geopolitical supply disruptions recede.
Reescalating tensions in the Gulf pushed oil higher recently, while central banks resumed their gold purchases Source: Bloomberg Finance L.P., DWS Investment GmbH as of 9/4/26
What’s driving the AI rally? Watch the video now.
3. Past performance of major financial assets
Total return of major financial assets year-to-date and past month
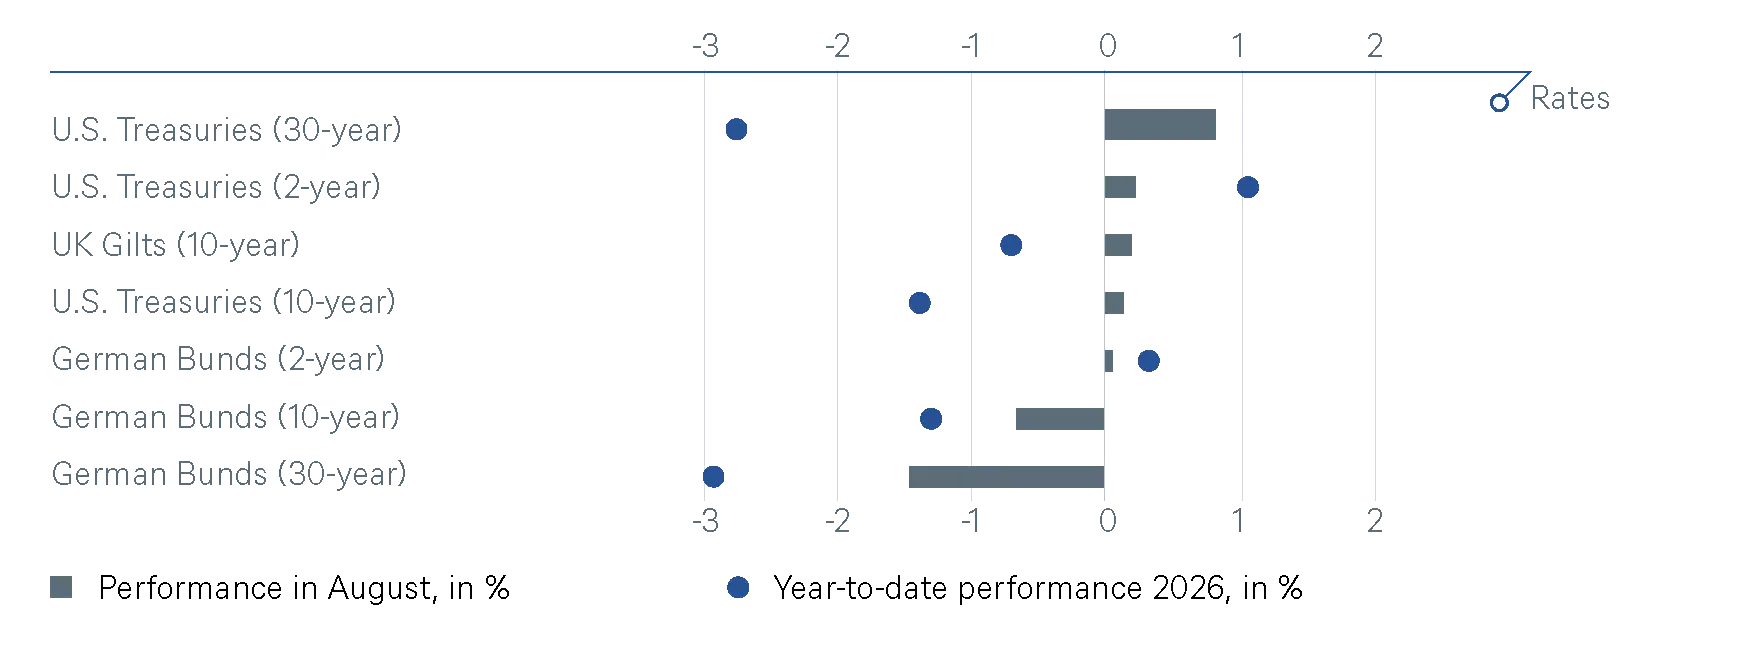


Past performance is not indicative of future returns. Sources: Bloomberg Finance L.P., DWS Investment GmbH as of 9/4/26
4. Tactical and strategic signals
The following exhibit depicts our short-term and long-term positioning.
| Rates | 1 to 3 months | through September 2027 |
|---|---|---|
| U.S. 2yr Interest Rate |  |  |
| U.S. 10yr Interest Rate | | |
| U.S. 30yr Interest Rate | | |
| Germany 2yr Interest Rate | | |
| Germany 10yr Interest Rate | | |
| Germany 30yr Interest Rate | | |
| Japan 2yr Interest Rate | | |
| Japan 10yr Interest Rate | | |
| UK 2yr Interest Rate | | |
| UK 10yr Interest Rate | | |
| UK 30yr Interest Rate | | |
| Spreads | 1 to 3 months | through September 2027 |
| EUR IG Corp | | |
| U.S. IG Corp. | | |
| EUR HY Corp. |  | |
| U.S. HY Corp. | | |
| EM Sovereigns | | |
| Italy 10yr[3] | | |
| Asia Credit | | |
Securitized / specialties | 1 to 3 months | through September 2027 |
| U.S. taxable municipal bonds[4] | | |
| Currencies | 1 to 3 months | through September 2027 |
| EUR vs. USD | | |
| USD vs. JPY | | |
Legend:
Tactical view (1 to 3 months)
The focus of our tactical view for fixed income is on trends in bond prices.
Positive view
Neutral view
Negative view
Strategic view through September 2027
The focus of our strategic view for sovereign bonds is on bond prices.
For corporates, securitized/specialties and emerging-market bonds in U.S. dollars, the signals depict the option-adjusted spread over U.S. Treasuries. For bonds denominated in euros, the illustration depicts the spread in comparison with German Bunds. Both spread and sovereign-bond-yield trends influence the bond value. For investors seeking to profit only from spread trends, a hedge against changing interest rates may be a consideration.
The colors illustrate the return opportunities for long-only investors.
- Positive return potential for long-only investors
- Limited return opportunity as well as downside risk
- Negative return potential for long-only investors