

Important security note: Warning of attempted fraud in the name of DWS
We have detected that fraudulent individuals are misusing the "DWS" trademark and the names of DWS employees on the internet and social media. These fraudsters are operating fake websites, Facebook pages, WhatsApp groups and Mobile Apps. Please be aware that DWS does not have any Facebook Ambassador profiles or WhatsApp chats. If you receive any unexpected calls, messages, or emails claiming to be from DWS, exercise caution and do not make any payments or disclose personal information. We encourage you to report any suspicious activity to info@dws.com, including any relevant documents and the original fraudulent email. Additionally, if you believe you have been a victim of fraud, please notify your local authorities and take steps to protect yourself.
CIO View Portfolio: Perspectives
8/13/2026
In our monthly Multi-Asset update we show the implementation of our CIO View in the CIO View model portfolio.

Vincenzo Vedda
Chief Investment Officer
Overview
Idea of the month
Semiconductor stocks have come under pressure as investors reassess the sustainability of AI-related capital expenditure and question whether hyperscalers can generate adequate returns on their massive investments. Yet the underlying drivers of the AI investment cycle remain largely intact. Computing power, data centers and digital infrastructure continue to require ever more advanced chips. The recent sell-off therefore appears less a reflection of weakening fundamentals than of elevated expectations being recalibrated. If AI spending remains robust, the correction could offer a relatively more attractive entry point into a sector that remains at the heart of the ongoing digital transformation.
Source: SOX Philadelphia Stock Exchange Semiconductor Index / Sources: Bloomberg Finance L.P., DWS Investment GmbH as of 8/6/26
Our take on duration & risk
Risk
Risks and opportunities appear broadly balanced in the near term. The macro environment remains supportive of equities and the earnings season has confirmed resilient corporate fundamentals. At the same time, market reactions to positive earnings surprises have been muted, indicating that much of the good news is already reflected in valuations. We therefore refrain from upgrading our stance to +1. Key risks include uncertainty around the Iran conflict, related pressure on bond yields and consumers, as well as less supportive seasonality in the coming months. With investor positioning and sentiment already positive, near-term upside may be limited.
We stick to our risk preference at neutral
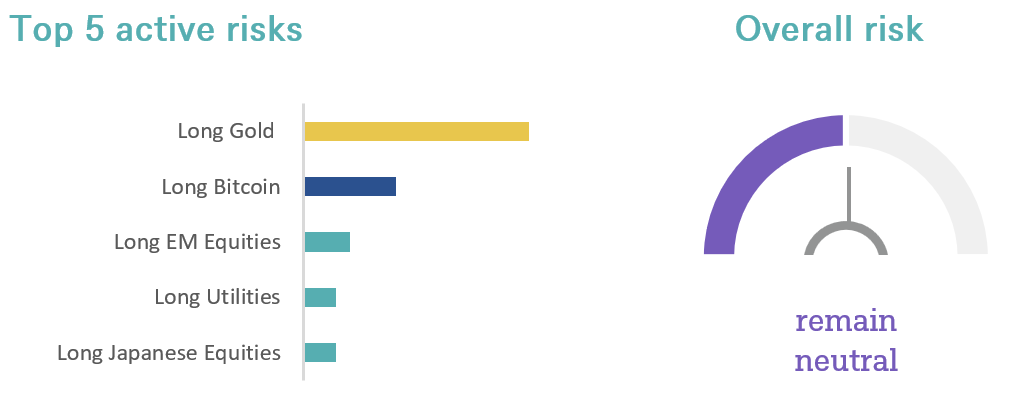
Source: DWS Investment GmbH as of August 5, 2026
Duration
We downgrade our duration preference from +1 to neutral while retaining a positive bias. Although yields remain elevated and we still believe markets are pricing too many rate hikes relative to our base case, particularly in the U.S., the near-term risk-reward profile has become more balanced. Higher oil prices and a more hawkish central bank narrative have kept yields high, while geopolitical risks could still push them higher. In a multi-asset context, duration currently offers limited diversification benefits. We therefore favor the shorter end of the curve, where carry and risk-adjusted return prospects appear more attractive, and maintain our steepening bias.
We lower our duration preference to neutral
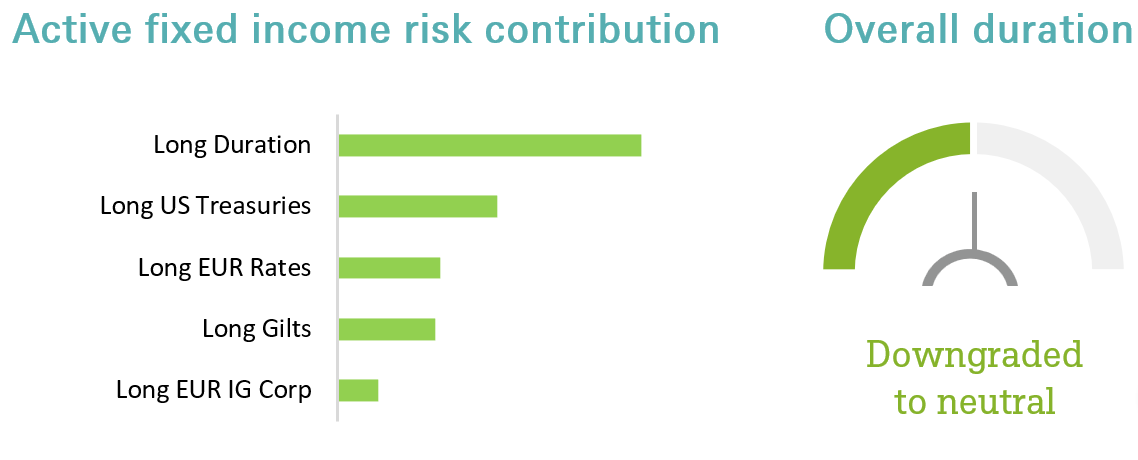
Source: DWS Investment GmbH as of August 5, 2026
What’s up in the segments?
Equities remain neutral overall, with a preference for emerging markets and Japan
We maintain a balanced risk preference in equities for now. While the sharp Momentum and AI-led correction has created selective opportunities, markets are still searching for direction amid the Q2 earnings season, uncertainty around the Iran conflict and renewed concerns about AI spending. Investor positioning, seasonal factors and the upcoming U.S. midterm elections could create temporary headwinds. Earnings revisions remain supportive, although expectations for 2026 and 2027 EPS growth remain ambitious by historical standards. Q2 earnings have so far surprised positively and are likely to remain a key market driver alongside geopolitical developments and the sustainability of AI-related capital expenditure. Regionally, we retain a +1 stance on Emerging Markets, supported by valuations that we consider attractive and stronger growth prospects, and maintain our positive view on Japan. We remain neutral on the U.S. and Europe. Among sectors, Utilities remain our preferred overweight, while Global Banks stand out for their combination of solid growth and attractive valuations in our view. In fixed income, we continue to favor EUR investment grade credit, supported by attractive all-in yields and supportive technicals. We also prefer EUR credit over USD credit, while EUR high yield appears less attractive given tight spreads. We favor selective exposure within emerging-market debt. Within currencies, we remain neutral on EURUSD in a multi-asset context.
Euro area is catching up
Source: Bloomberg Finance L.P., DWS Investment GmbH as of 8/6/26
Source: Bloomberg Finance L.P., DWS Investment GmbH as of 8/6/26
CIO View Model Portfolio positioning vs. anchor
This allocation shows how we implement the above-mentioned CIO View into a Multi-Asset portfolio of liquid securities.
This allocation may not be suitable for all investors and can be changed at any time without notice. Source: DWS Investment GmbH, as of August 5, 2026. The anchor allocation refers to the strategic asset allocation, while the portfolio positioning refers to the tactical asset allocation. Rounded figures. Including equity derivatives.
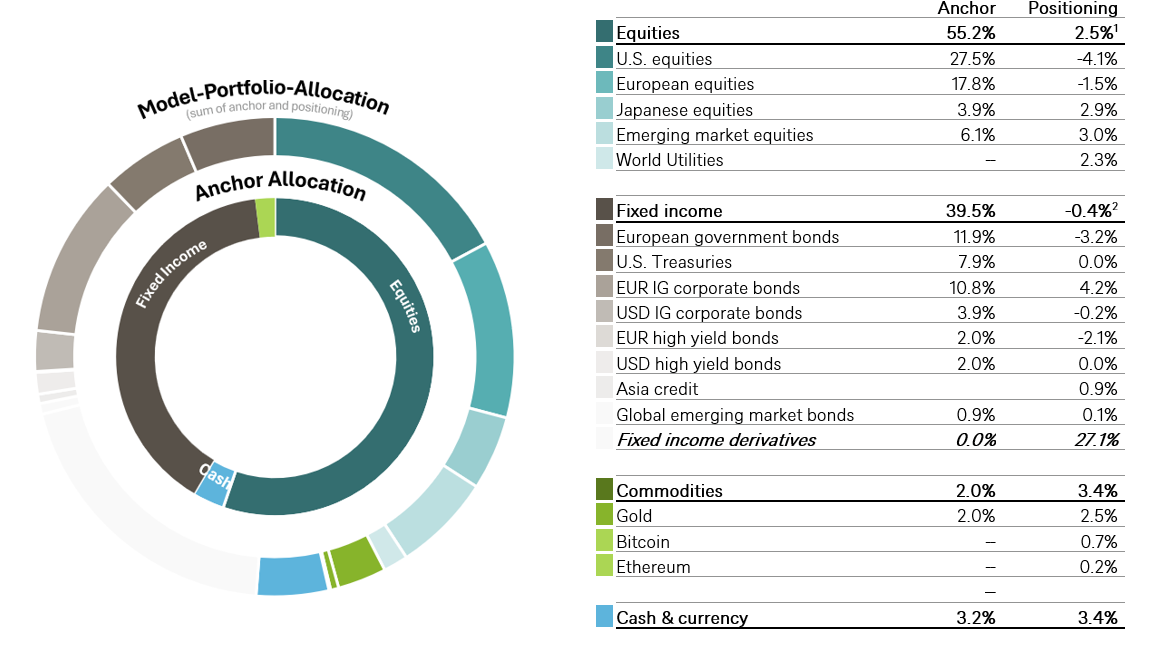
1 Total excluding interest rate derivatives
2 (derivatives are included in the positioning figures at a subordinate level).