
Important security note: Warning of attempted fraud in the name of DWS
We have detected that fraudulent individuals are misusing the "DWS" trademark and the names of DWS employees on the internet and social media. These fraudsters are operating fake websites, Facebook pages, WhatsApp groups and Mobile Apps. Please be aware that DWS does not have any Facebook Ambassador profiles or WhatsApp chats. If you receive any unexpected calls, messages, or emails claiming to be from DWS, exercise caution and do not make any payments or disclose personal information. We encourage you to report any suspicious activity to info@dws.com, including any relevant documents and the original fraudulent email. Additionally, if you believe you have been a victim of fraud, please notify your local authorities and take steps to protect yourself.
YenDrain: The price of Japan's capital outflows
25/08/2026
More of Japan's capital is being put to work abroad, with lasting consequences for the yen
IN A NUTSHELL
- The yen remains near historic lows in real terms, but its weakness is about more than just low interest rates.
- Over several decades Japan has evolved from a traditional export-driven economy into one of the world's largest exporters of capital.
- Interventions by Japan and the United States may help stabilise the yen. A lasting turnaround, however, would likely require more attractive domestic investment opportunities that encourage a greater share of capital to remain at home.

Vincenzo Vedda
Chief Investment Officer

Why the yen story is about more than interest rates
At the end of July, Japan and the United States intervened in foreign exchange markets after the yen fell to its weakest level in nearly four decades. The move highlighted growing concern about the currency's weakness, but it also raised a broader question: why has the yen remained under such persistent pressure despite Japan's strong external position and repeated policy efforts to support the currency?
The answer lies in a profound shift in Japan's economic model. Over recent decades, the country has evolved from a traditional export powerhouse into one of the world's largest exporters of capital. As corporations, institutional investors and households increasingly invested abroad, a growing share of Japanese wealth became tied to overseas assets and earnings rather than domestic opportunities.
Viewed through this lens, interest-rate differentials and foreign-exchange interventions remain important, but they are only part of the story. Japan's emergence as a capital-export nation has reshaped the long-term drivers of the yen. What conditions would be required for a more lasting reversal of the trend?
1. Japan's long transition to a capital-exporting economy
Few developments in global currency markets have been as striking as the yen's long-term decline. Japan is one of the world's wealthiest economies, with substantial household and institutional savings, and has ranked among the world's largest creditor nations for decades. Yet, as shown in the following Chart, the yen's real effective exchange rate has fallen by roughly two-thirds since the mid-1990s. The currency of one of the world's most advanced industrial economies is therefore weaker in real terms than it has been in decades.[1]
The most common explanation is monetary policy, which has undoubtedly played an important role in the yen's downward trajectory. Yet this alone does not fully explain why the real exchange rate has continued to weaken over a period of three decades. To understand the forces behind the longer-term decline, however, we need to look beyond the Bank of Japan (BoJ) and towards the country's capital flows.
Sources: Bloomberg Finance L.P., DWS Investment GmbH as of 8/11/26
1.1 The turning point: Japan's lost decades
The roots of the yen’s weakness can be traced back to the early 1990s. Following the collapse of Japan's stock-market and real-estate bubble, the economy entered a prolonged period of weak growth, low inflation and limited domestic investment opportunities. For companies that had previously benefited from Japan's economic boom and industrial strength, the environment changed fundamentally. Many shifted production and investment overseas, making international operations an integral part of their business models.
This also altered the role of the yen. In earlier decades, Japan's external strength was closely tied to exports produced in the country, which generated demand for yen. As Japanese companies expanded internationally, the link between economic success and demand for the yen gradually weakened. That process continues, with Japan’s companies continuing to build facilities outside the country today. Their outward foreign direct investment reached around 5% of nominal GDP in spring 2026, the highest level since Bloomberg's data series began.[2]
1.2 Japan looks abroad for returns
At the same time, Japanese investors changed the way they allocate investment capital. Insurers, pension funds, banks and other institutional investors faced a common challenge: worthwhile returns on relatively safe investments were increasingly difficult to find at home, making it hard to fulfill long-term obligations to an aging population. Investing abroad therefore became not just more attractive but, in many cases, essential to these institutions’ business models. Japanese savings were increasingly deployed in global markets.
Today, Japan is one of the world's largest net creditor nations. This underpins the country's finances but means a growing share of income is now generated by overseas foreign currency investments rather than by traditional exports.
1.3 What this means for the yen
This transformation has important implications for the yen. Income generated from overseas investments is often reinvested locally rather than automatically repatriated to Japan. As a result, external economic strength no longer necessarily translates into a stronger currency.
At the same time, the internationalization of Japanese savings has broadened. In addition to corporations and institutional investors, households have also increased their exposure to foreign assets, supported by reforms that have made access to international funds and equity markets easier.
The yen's long-term weakness in real terms reflects this structural shift. Japan exports not only goods and technology but also capital on a large scale. If the weakness of the currency is primarily a consequence of these capital flows, interest-rate moves by the Bank of Japan or foreign-exchange interventions can influence the trend only temporarily. A more durable recovery would likely require Japan to offer better investment prospects at home and give savers stronger reasons to keep more of their capital in the country.
2. How the Bank of Japan amplified the trend
2.1 Japan as a monetary-policy pioneer
Japan’s long experiment with ultra-accommodative monetary policy did not create the country’s shift towards capital exports, but it shaped the environment in which that shift unfolded. Faced with weak growth, low inflation and recurring deflationary pressures after the asset-price bubble burst in the 1990s, the Bank of Japan became one of the first major central banks to adopt unconventional policy tools.
This made Japan a monetary-policy pioneer. Zero interest rates, large-scale bond purchases (quantitative easing), negative rates and later yield-curve control helped keep Japanese interest rates well below those in most other developed markets for long periods. What began as an extraordinary response to economic weakness gradually became a defining feature of Japan's monetary-policy landscape. Over time, the combination of very low rates and limited domestic return opportunities reinforced the incentive to allocate capital abroad.
2.2 The yen as a funding currency
The consequences extended far beyond Japan. Low funding costs made the yen one of the world's leading funding currencies. Investors could borrow cheaply in yen, convert the proceeds into foreign currencies and invest in assets offering higher expected returns, including bonds, equities and other assets abroad. The carry trade became an established feature of global financial markets, adding to the downward pressure on the Japanese currency.
This dynamic became particularly visible during the so-called Abenomics era after 2013. Under Prime Minister Shinzo Abe and BoJ Governor Haruhiko Kuroda, monetary easing was intensified significantly. Large-scale BoJ asset purchases, negative interest rates and yield-curve control were designed to break deflationary expectations and revive economic momentum. The policy mix reinforced expectations that Japanese rates would remain exceptionally low for an extended period. That strengthened the yen’s role as a funding currency and encouraged investors to seek higher returns abroad. During this period, the decline of the yen in real terms accelerated noticeably.
A second episode of pronounced weakness followed the Covid pandemic. While the Federal Reserve and many other central banks raised interest rates aggressively, the Bank of Japan initially maintained its ultra-accommodative stance. Interest-rate differentials reached their widest levels in decades, further increasing the incentive for Japanese investors to allocate capital abroad. These episodes show how monetary divergence can intensify capital outflows and exchange-rate pressure when structural incentives to invest abroad are already in place. .
2.3 Monetary policy: amplifier rather than root cause
This distinction is crucial when assessing the long-term trajectory of the yen. Monetary policy helps explain many of the larger swings in the exchange rate. It does not, however, explain why the yen was, in real terms, already on a structural downward trajectory long before Abenomics, the adoption of negative interest rates or the most recent tightening cycle in the U.S. The foundations of that trend had already been laid in the years following the collapse of Japan's asset-price bubble. Japanese companies shifted production overseas, institutional investors built global portfolios and the economy increasingly evolved into a net exporter of capital.
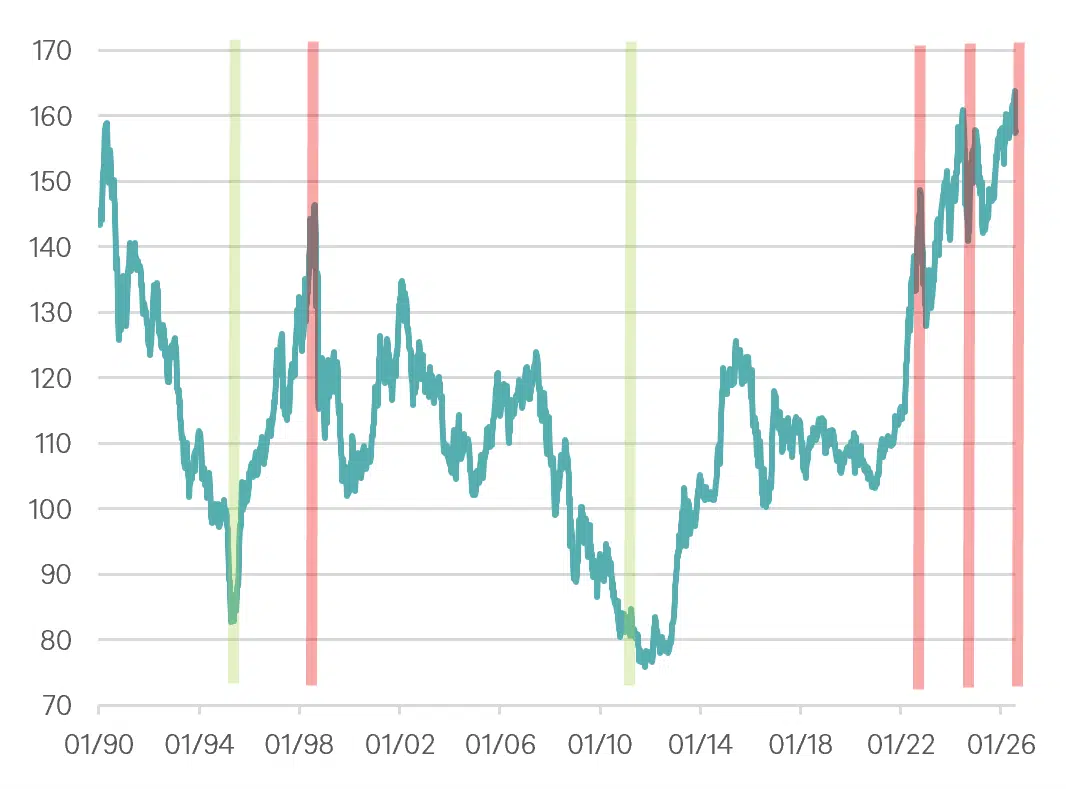
Monetary policy and capital flows should not be viewed as competing explanations of yen weakness. Rather, they reinforce one another. "The most pronounced periods of yen depreciation frequently coincided with episodes of significant monetary policy divergence. However, the long-term trend began much earlier. For much of this period, monetary policy acted as an amplifier of an already established model of capital exports," says Xueming Song, Currency Strategist at DWS. The following charts show that yield differentials and interventions can affect the timing and magnitude of yen movements, but they do not fully explain the longer-term trend.
Interest-rate differentials and interventions shape the yen (JPY)
USD/JPY and important market interventions (green: yen selling / red: yen buying)
Sources: Bloomberg Finance L.P., DWS Investment GmbH as of 8/11/26
Developments this summer offer a particularly clear illustration of this relationship. Although the Bank of Japan has begun normalizing policy and has raised its policy rate to 1.0%, it left rates unchanged immediately following the latest market interventions. The subsequent partial recovery of the yen demonstrated how sensitive the currency remains to interest-rate expectations, at least in the short term. Even after the intervention, the yield differential relative to the U.S. remained substantial. The underlying monetary and structural pressures on the yen therefore remain in place.
2.4 Interventions: a strong signal but limited structural impact
The coordinated interventions at the end of July 2026 altered the short-term backdrop but did little to change the broader picture. Japan first entered the market on July 30, using dollars to make large-scale yen purchases. The following day, the United States joined the effort in a coordinated operation. Washington's participation was particularly noteworthy. It marked the first joint yen-buying intervention by the two countries since 1998. The U.S. sold euros from its Exchange Stabilization Fund, while Japan, as is typically the case, relied on its dollar reserves to finance its purchases. Both governments also signaled their willingness to intervene again should what they called “disorderly” market conditions re-emerge.
The market reaction was initially significant. The yen appreciated from nearly 164 per U.S. dollar to around 155 at its strongest point. Less than a week later, however, it had already weakened back to roughly 158. The episode shows that coordinated intervention can force investors to unwind one-sided positions and interrupt a rapid decline. It does not automatically create a lasting reversal of the trend.
For that to happen, the underlying fundamentals would need to change. Despite a temporary narrowing, the yield gap between U.S. Treasuries (USTs) and Japanese government bonds (JGBs) remains substantial. At the same time, elevated levels of outward foreign direct investment and the international allocation of Japanese savings continue to exert structural pressure on the currency. Recent policy measures once again underscore the importance of distinguishing between short-term market stabilization and a durable shift in long-term trends.
A further rate increase in September, and potentially a faster pace of tightening thereafter if economic conditions warrant it, could provide additional support for the yen by narrowing interest-rate differentials. As Governor Kazuo Ueda has indicated, however, the path of policy will depend on incoming data. Monetary tightening may help ease short-term pressure on the currency, but a more lasting recovery would likely require a broader improvement in Japan’s domestic investment prospects.
3. Can Japan reverse the trend?
The coordinated intervention by Japan and the United States at the end of July after the currency fell to its weakest level in nearly four decades showed that persistent yen weakness is no longer merely a foreign-exchange-market concern. For Japan, much more is at stake than short-term exchange-rate movements. A weak yen supports exporters and raises the yen value of foreign earnings, but it also makes imports more expensive and erodes household purchasing power. The strain on consumers has turned the currency's weakness into a domestic political issue, pushing measures to support household finances up the policy agenda. The planned reduction in the consumption tax on food from 8% to 1% for two years from next April can be understood in this context. This also helps explain recent efforts by policymakers to encourage institutional investors to commit more capital at home.
Political encouragement alone, however, is unlikely to reverse the trend. Investors ultimately base long-term decisions on expected returns, diversification benefits and the broader regulatory environment. As long as more attractive investment opportunities can be found outside Japan, a large share of capital is likely to continue to be directed towards international markets.
The debate about the yen is therefore about more than exchange rates or monetary policy. Higher interest rates and occasional interventions may support the currency and curb excessive market moves. But a more durable recovery would likely require Japan to become attractive enough again for investors to retain a larger share of capital domestically. Unless that happens, the structural forces that have shaped the yen for decades are likely to remain in place.